
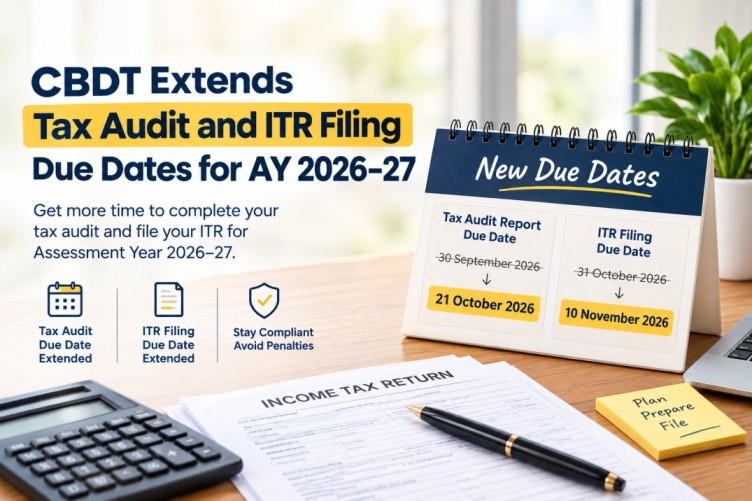
The Central Board of Direct Taxes (CBDT) has announced a major relief for taxpayers whose accounts are subject to audit under the Income-tax Act, 1961, for Assessment Year (AY) 2026–27. The announcement, dated 28 September 2026, extends both the tax audit report filing deadline and the corresponding income tax return (ITR) filing deadline.
The tax audit report deadline has been extended from 30 September 2026 to 21 October 2026, while the ITR filing deadline for the covered taxpayers has been moved from 31 October 2026 to 21 November 2026.
The extension gives eligible taxpayers, businesses, chartered accountants, and tax professionals additional time to complete pending audits, verify financial records, and submit their income tax returns.
1. CBDT Announces Revised Tax Compliance Deadlines
The revised dates announced by the CBDT are as follows:
| Compliance requirement | Earlier due date | Revised due date |
| Tax audit report for AY 2026–27 | 30 September 2026 | 21 October 2026 |
| ITR filing for specified audit cases | 31 October 2026 | 21 November 2026 |
The extension covers the relevant categories of taxpayers specified in the CBDT’s announcement. It should not be interpreted as a blanket extension for every individual, salaried employee, or non-audit taxpayer.
The CBDT has also stated that a formal order or notification giving effect to the extension will be issued separately. Taxpayers should check the official notification for the final legal wording and applicability.
2. Who Is Eligible for the Extended ITR Filing Deadline?
The extension applies to persons covered under the relevant category referenced in Explanation 2 to Section 139(1) of the Income-tax Act, 1961, as specified in the CBDT announcement. These are taxpayers whose accounts are required to be audited under the applicable provisions.
The affected taxpayers may include:
- Businesses and proprietorships required to undergo a tax audit.
- Partnership firms and LLPs whose accounts are subject to applicable audit requirements.
- Companies and other entities covered by the relevant statutory provisions.
- Other specified taxpayers required to furnish audited returns under the Income-tax Act.
Whether a particular taxpayer qualifies depends on the applicable audit provisions, nature of income, turnover or receipts, and other statutory conditions.
Important: Taxpayers who are not covered by this specific extension should continue to follow the due dates applicable to their category. The extension does not automatically change the deadlines for all ITR forms or all taxpayers.
3. Tax Audit Report Due Date Extended to 21 October 2026
The CBDT has extended the specified date for furnishing the audit report under the Income-tax Act from 30 September 2026 to 21 October 2026 for the relevant taxpayers.
A tax audit involves examining financial records and verifying whether the taxpayer has complied with applicable income tax provisions.
Depending on the taxpayer’s circumstances, the prescribed audit documentation may include Form 3CA or Form 3CB, along with Form 3CD, where applicable.
Taxpayers and their chartered accountants should use the additional time to:
- Complete the verification of books of accounts and financial statements.
- Reconcile bank statements, sales records, expenses, and other financial information.
- Review deductions, disallowances, and tax-related adjustments.
- Verify TDS and advance tax information.
- Complete and furnish the applicable tax audit report through the income tax e-filing portal.
The extended deadline provides additional time for audit-related compliance, but taxpayers should avoid waiting until the last few days to submit their reports.
4. ITR Filing Deadline for Audit Cases Extended to 21 November 2026
Along with the tax audit report deadline, the CBDT has extended the income tax return filing deadline for the specified audit cases from 31 October 2026 to 21 November 2026.
This is particularly relevant for businesses and professionals who need to prepare their ITR using audited financial statements and the information contained in the tax audit report.
The additional time can help taxpayers complete the following activities:
- Verify income, expenditure, and taxable profits.
- Ensure that financial statements are consistent with the tax audit report.
- Reconcile tax credits and tax payments.
- Review applicable deductions, exemptions, and other tax adjustments.
- Complete the relevant ITR form and submit the return within the revised deadline.
Taxpayers should also ensure that any outstanding tax liability is calculated and paid in accordance with the applicable provisions.
Filing the return and paying the tax due are separate compliance requirements. An extension of the filing date should not automatically be treated as a waiver of interest or other statutory obligations.
5. What Should Taxpayers Do After the Extension?
Although the extension provides additional time, taxpayers should use this period to complete pending compliance rather than postpone their filing preparations.
| Action | Recommended step |
| Financial records | Finalise books of accounts and financial statements. |
| Tax audit | Coordinate with the chartered accountant to complete the applicable audit report. |
| Tax payments | Review outstanding tax, TDS, and advance tax obligations. |
| Return preparation | Match ITR details with audited accounts and tax records. |
| Final submission | File the applicable ITR and retain the acknowledgement. |
Taxpayers should also monitor the Income Tax Department’s official website for the formal CBDT order or notification implementing the revised dates.
Frequently Asked Questions (FAQs)
1. What is the new tax audit report due date for AY 2026–27?
The CBDT has extended the tax audit report deadline from 30 September 2026 to 21 October 2026 for the taxpayers covered by the announcement.
2. What is the revised ITR filing last date for audit cases?
The revised income tax return filing deadline for the specified audit cases is 21 November 2026, instead of 31 October 2026.
3. Does the extension apply to salaried individuals?
Not automatically. The announcement specifically concerns the relevant categories of taxpayers subject to audit. Salaried individuals who are not covered by the specified provisions should follow the due date applicable to their ITR category.
4. Does the extension apply to all businesses?
No. Eligibility depends on whether the taxpayer falls within the categories covered by the CBDT announcement and the applicable statutory audit requirements.
5. Has the CBDT issued a formal notification?
Conclusion
The press release states that a formal order or notification will be issued separately. Taxpayers should refer to the official order for the precise scope and implementation of the extension.
The CBDT’s announcement on 28 September 2026 provides additional time for eligible taxpayers to complete their tax audit and income tax return filing requirements for AY 2026–27.
The revised deadlines are 21 October 2026 for the tax audit report and 21 November 2026 for the ITR in the specified audit cases.
Businesses, professionals, and tax practitioners should review their pending compliance, coordinate with their chartered accountants, and verify the formal notification before relying on the revised dates.
For assistance with tax compliance, business accounting, and financial documentation, taxpayers can consult a qualified tax professional.
Source: CBDT press release dated 28 September 2026, as reported by Moneycontrol. Verify the formal CBDT order for the exact statutory scope.
We Are Guide you all step how to Deal with Tax Audit and ITR Filing
